Collectors have form letters and lawyers. Now you have someone in your corner.
We dispute collection accounts, and repossession balances still owed to the auto lender, for Texans by USPS Certified Mail. You pay $100 only when the collector confirms in writing that it's stopping collection, the lender waives the balance or agrees in writing to stop collecting, or the account comes off your credit report. Nothing is charged until then.
About 5 minutes • No credit report needed
Results not guaranteed. Individual outcomes vary. You have the right to dispute inaccurate information in your credit report directly with the credit bureaus, collection agencies and lenders at no cost.
Complete the form to begin your dispute process. Note: Each account you list can be with a collection agency, or, for a car that was repossessed or voluntarily surrendered, still with the auto lender.
Currently serving Texas residents only
Real letters from collectors who stopped collecting after a dispute. See them
Built by the team behind Cheating Debt, helping Texans with their credit since 2016. Results vary.
Pay Only If Collection Stops — nothing is charged today. Once your 3-business-day cancellation period ends, we mail your dispute letter within 3 business days and pull your credit report under your power of attorney to track what actually happens. You only pay $100 on a Qualifying Outcome — the agency confirms in writing it's ceasing collection, or your credit report shows the account is no longer being reported.
Complete a simple online form with your information and the accounts you want disputed. Your card is stored securely on file — nothing is charged today.
Your 3-business-day cancellation period comes first: cancel for any reason and you owe nothing. Once it ends, we write your personalized dispute letter.
Your letter goes out by USPS Certified Mail within 3 business days after your cancellation period ends. You'll receive a tracking number to follow delivery.
Under your limited power of attorney, we request your credit file from Equifax, Experian, and TransUnion once you've uploaded your ID and proof of address (we email you a secure link right after you sign up) — and again if the agency doesn't respond and we send a follow-up — to check whether the account quietly stopped being reported, and to flag any other accounts worth disputing.
If a collector can't verify the debt, the law says it has to stop collecting until it does. You pay $100 if the collector confirms in writing that it's ceasing collection, the lender waives the balance or agrees in writing to stop collecting, or a credit report we pull for you shows the account is no longer being reported — whichever happens first. If none of those happens, you owe nothing.
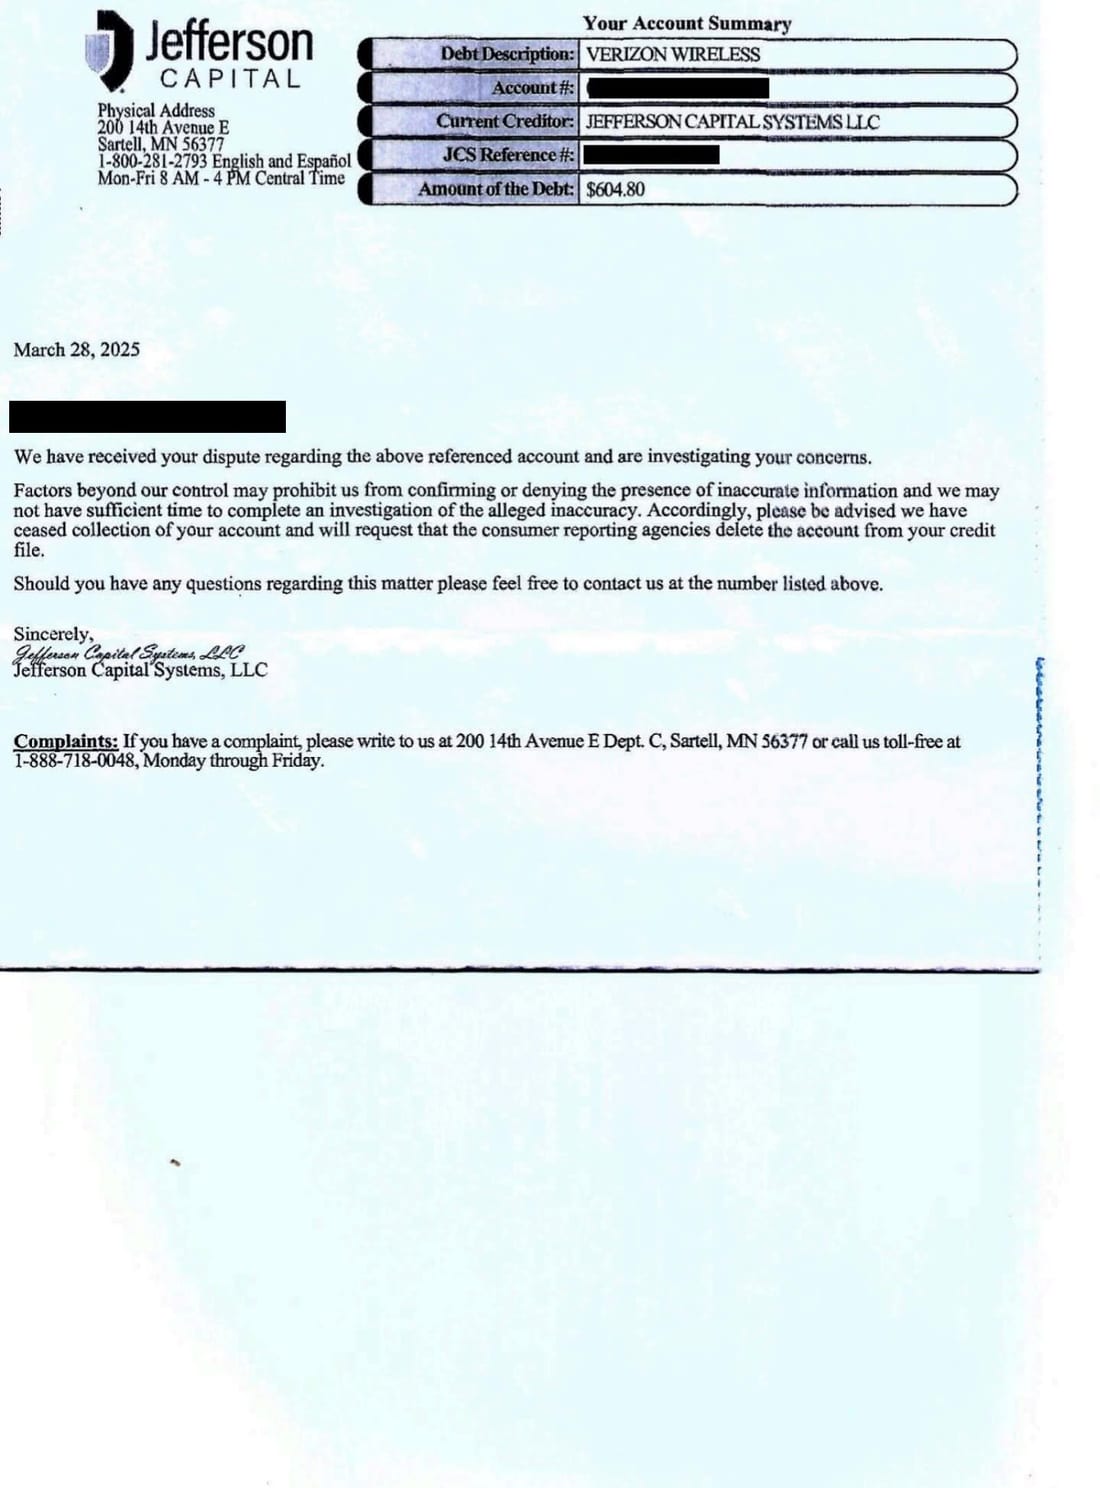
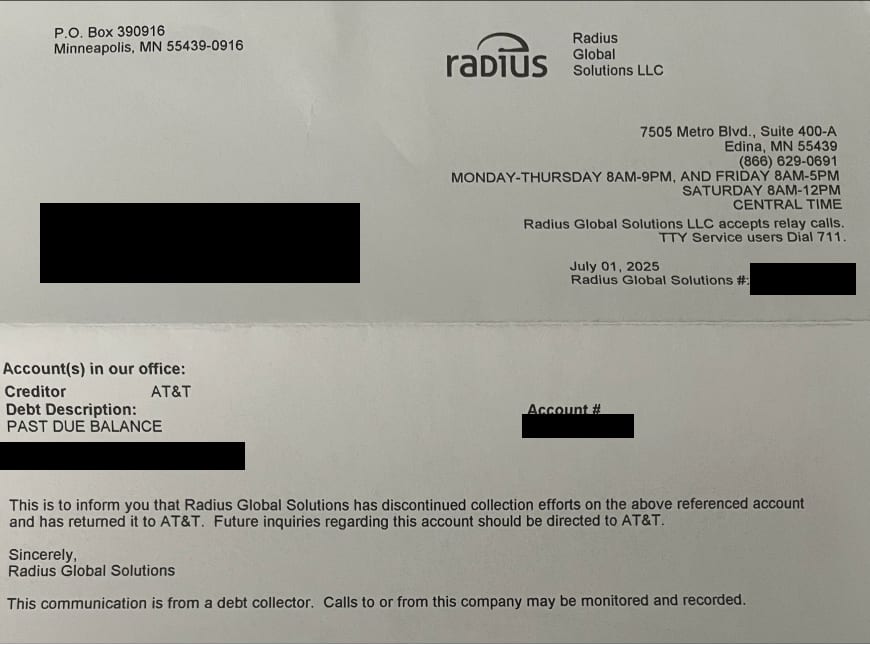
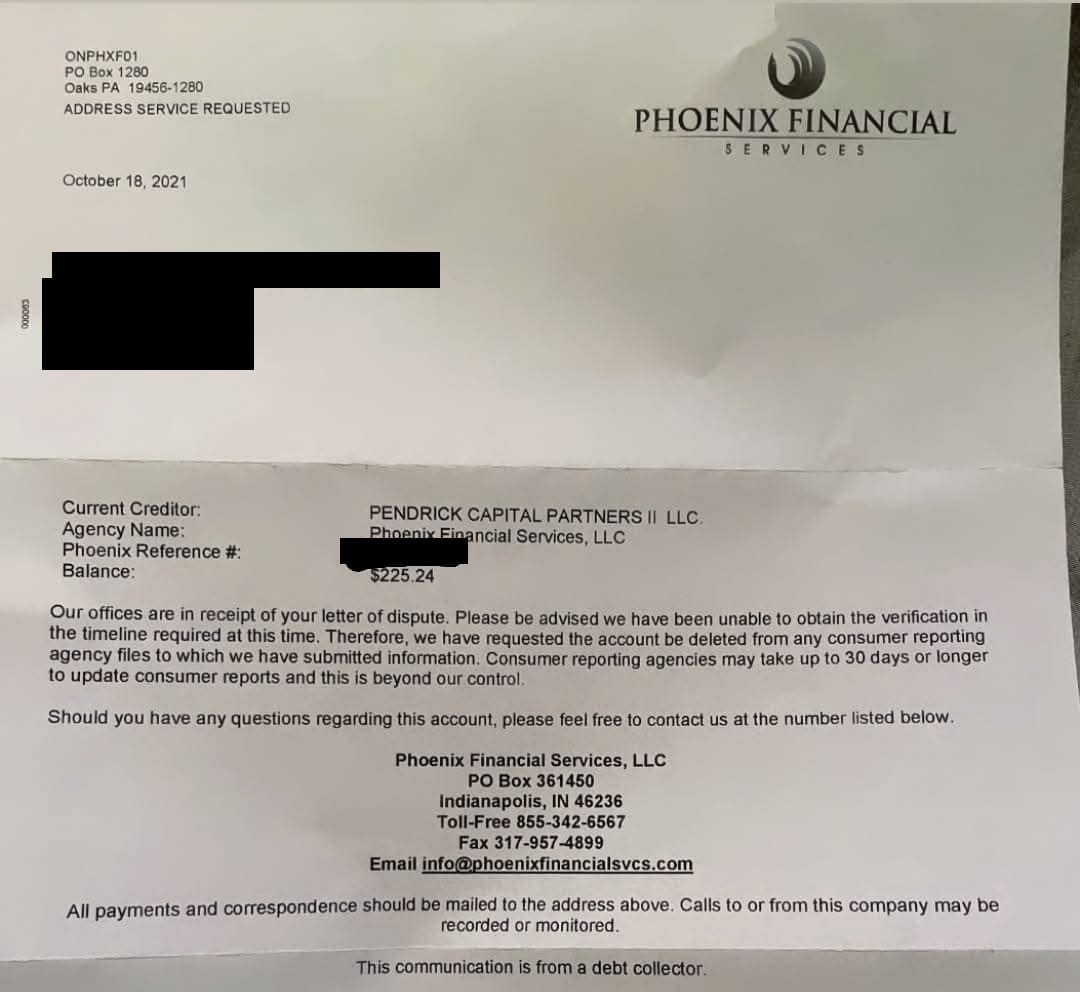
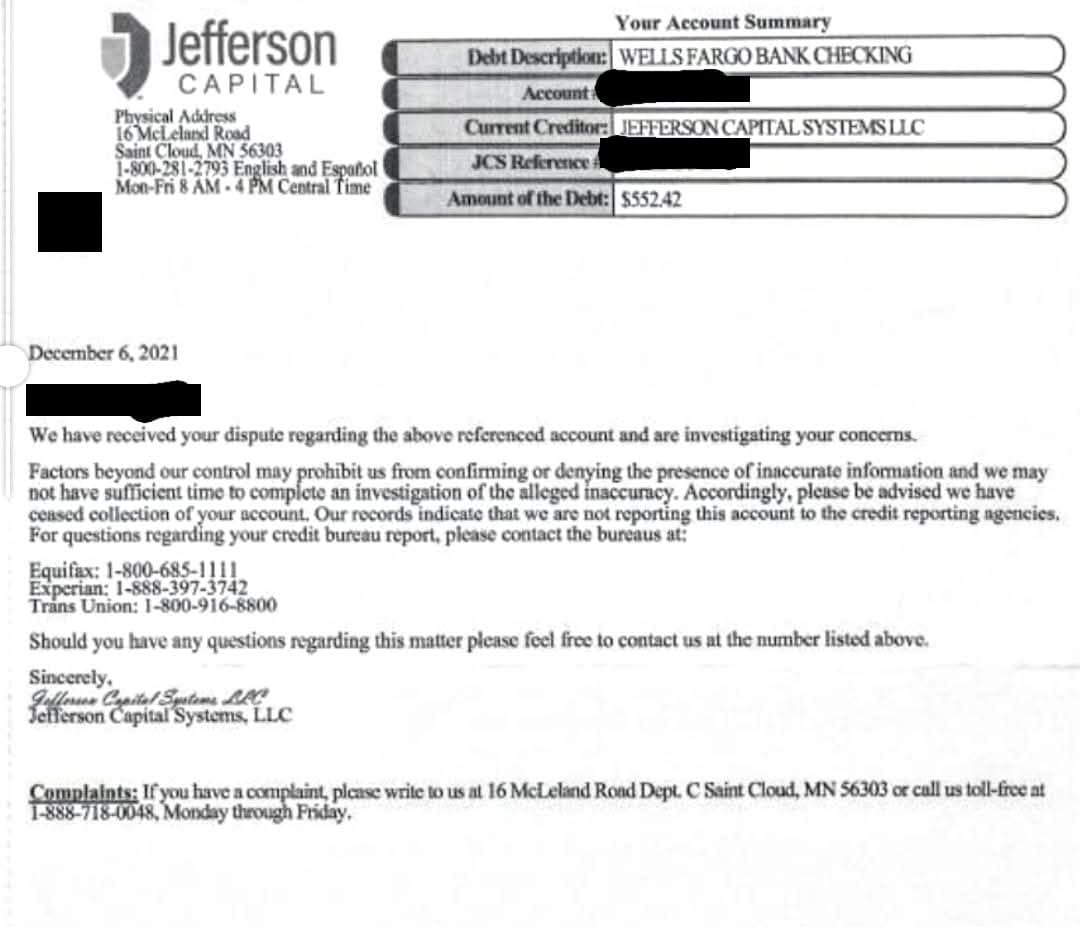
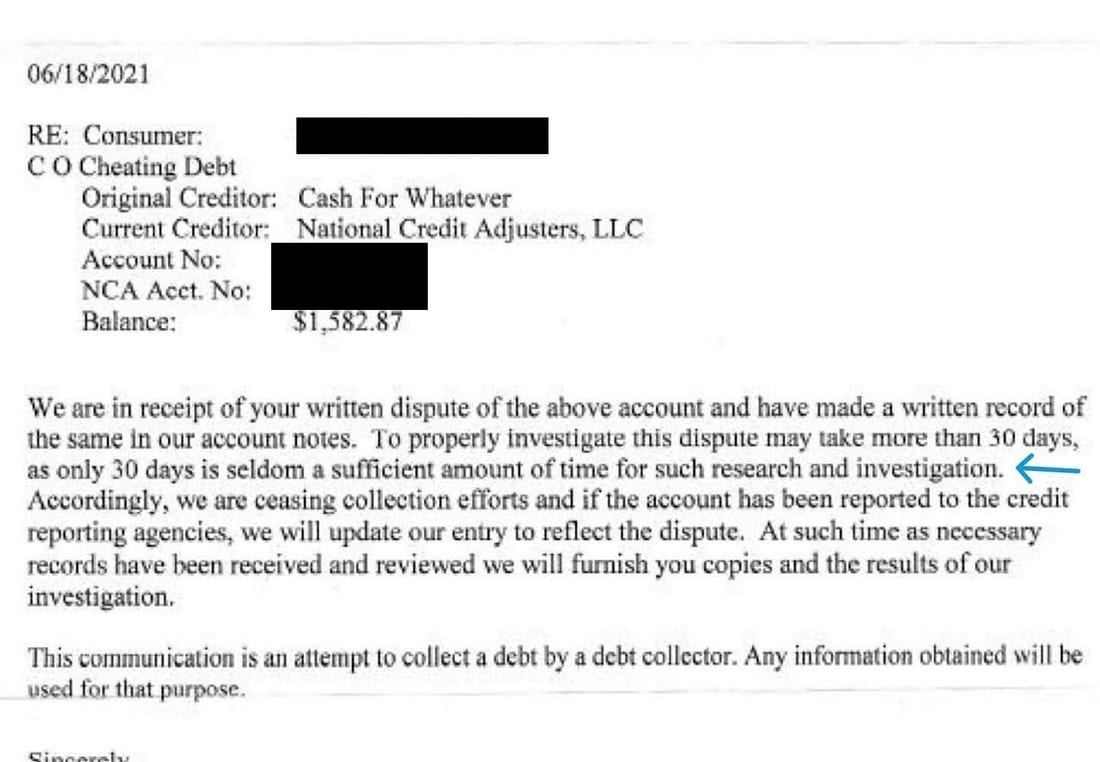
Each of these collectors put in writing that it stopped collecting after a dispute. Names and account numbers are blacked out.
Stopped collecting and asked the credit bureaus to delete the account.
Stopped collecting and returned the account to the original creditor.
Couldn't verify the debt in time and asked the credit bureaus to delete it.
Stopped collecting, and says it isn't reporting the account.
Ceased collecting while it investigates the dispute. For a letter like this, the $100 applies only once the account comes off the credit report.
These show what a collector's response can look like, not what will happen with yours: many collectors never answer, or keep reporting the account. The 2021 letters come from the Cheating Debt dispute work that Dispute on Demand grew out of, which is why one is addressed to Cheating Debt. Every account is different, and no one can remove accurate, current, verifiable information.
Paying for something without knowing if it will work is the worst part of getting help. So we take that risk. We believe in this process enough to only get paid when it works.
Certified mail, printing, and a follow-up letter when an account needs another round. If you paid per letter, at $25–35 each, a stubborn account could add up fast.
$100, only when the collector confirms in writing that it's stopping collection, the lender waives the balance or agrees in writing to stop collecting, or a credit report we pull for you shows the account is gone. If none of those happens, you owe nothing.
You get your USPS tracking number, and we read the response for you and tell you what it means.
Disputing is your right, at no cost. We're here if you'd rather not take on a collector alone.
We've helped Texans with their credit since 2016. Like most credit help, we started with disputes through the credit bureaus. But we noticed some accounts didn't seem to get a real investigation; they just came back marked “disputed.”
So we went to the source. The Fair Debt Collection Practices Act lets you ask a collector to validate a debt: that it's yours, who owned it, how much is owed, and that they followed the required notice process. Dispute on Demand does exactly that, by certified mail.
“My favorite part is when someone who's never heard of these laws gets to watch them work.”
Brent Rankin, founder
Read our story → Not sure where to start? Get a free Debt Cheat Sheet
Here's exactly what happens after you sign up
You Sign Up
You read your rights, sign your agreement, and your card is stored securely on file. Nothing is charged today.
Letter Mailed — Still $0 Charged
After your 3-business-day cancellation period ends, your dispute letter ships via USPS Certified Mail within 3 business days. You'll get a tracking number. Nothing is charged yet.
Letter Delivered
The collection agency or lender receives your certified dispute letter. You can follow it with your tracking number.
The Collector or Lender Responds (Or Doesn't)
The law doesn't set a deadline for collectors to answer, but if one can't verify the debt, it has to stop collecting until it does. Many respond within 30 to 45 days; some never do. A lender asked to explain a repossession deficiency has 14 days under Texas law; our other lender letters ask for an answer within 30 days. We send a follow-up when an account needs one.
$100 Charged Per Qualifying Outcome
When the agency confirms in writing that it's ceasing collection, or your credit report shows the account is no longer being reported — whichever happens first — we notify you and charge $100 to the card on file. If none of those happens, you pay nothing.
Timeline is approximate. Actual results may vary based on agency response time and credit bureau processing.
Learn your rights and how to dispute accounts from specific collection agencies.
Straight answers, so you can decide if Dispute on Demand is right for you.
Dispute on Demand is built by the team behind Cheating Debt, which has helped Texans with their credit since 2016. It grew out of Cheating Debt's own dispute work. Read our story.
Dispute On Demand disputes negative accounts for Texans by certified mail: with the collection agency, or, after a car repossession, with the auto lender when it still holds the balance. We also request your credit report from the three bureaus under your power of attorney to track the results. We operate on a Pay Only If Collection Stops model — you pay $100 only on a Qualifying Outcome: the collection agency confirms in writing that it is ceasing collection, the original lender waives the balance or agrees in writing to stop collecting, or a credit report we pull shows the account is no longer being reported. Nothing is charged today.
Collection accounts held by a third-party collection agency: medical bills, charged-off credit cards, repossession balances, personal and payday loans, apartment balances, utilities and more. If your car was repossessed or voluntarily surrendered and the auto lender still holds the balance, we can dispute that with the lender too. For other accounts still with the original lender, a free dispute with the credit bureaus is usually the best first step.
You complete the online form with your information and the accounts you want disputed, whether each is with a collection agency or, after a repossession, the auto lender. Your card is securely stored on file but nothing is charged. After your 3-business-day cancellation period ends, we prepare your dispute letter and mail it by USPS Certified Mail within 3 business days. Under your power of attorney, we also request your credit report from Equifax, Experian, and TransUnion when the letter is mailed, and again if a follow-up dispute is needed. If the collector confirms in writing that it is ceasing collection, the lender waives the balance or agrees in writing to stop collecting, or your credit report shows the account is no longer being reported, you pay $100. If none of those happens, you pay nothing.
We use a Pay Only If Collection Stops model — $100 only on a Qualifying Outcome: the collection agency confirms in writing that it is ceasing collection, the original lender waives the balance or agrees in writing to stop collecting, or a credit report we pull for you shows the account is no longer being reported. No monthly fees, no hidden charges, and nothing is charged if none of those happens.
You need your basic personal information (name, address, date of birth) and the name of the collection agency or lender reporting the account. No credit report is required to get started.
Yes, for now. Dispute on Demand serves Texas residents only. We're a registered and bonded Texas credit services organization, and we're focused on doing that well before expanding to other states.
We prepare your dispute letter right after your 3-business-day cancellation period ends, and mail it by USPS Certified Mail within 3 business days. The FDCPA doesn't give collectors a deadline to answer; if one can't verify the debt, it has to stop collecting until it does. Many respond within 30 to 45 days. A lender asked to explain a repossession deficiency has 14 days under Texas law.
For a collection agency, we use the rights the Fair Debt Collection Practices Act and the Texas Debt Collection Act give you to ask it to validate a debt. For an auto lender after a repossession, we use Texas's rules for repossession sales and deficiencies, which require the lender to explain in writing how it calculated what it says you still owe, Texas debt collection law, which also covers creditors collecting their own accounts, and the Fair Credit Reporting Act for how the account is reported. The letters on this site are real, redacted letters collectors sent after our disputes. Every account is different, and no one can guarantee a result or remove accurate, current, verifiable information.
No credit repair service can legally guarantee the removal of accurate, current, and verifiable information. Dispute On Demand prepares and delivers dispute letters under the laws that apply to each account, but outcomes depend on each individual account and how the collection agency or lender responds. Past results shown on this site are real client experiences and do not guarantee future results.
Yes. We guide you through the process and review any responses you get from collection agencies and lenders.
Yes. You get a USPS tracking number to follow your letter's delivery.
Yes. You have the right to cancel without penalty or obligation within three (3) business days of signing your agreement, as required by federal law. After that, you can end your agreement any time by email. If your letter hasn't been mailed yet, we won't mail it and you owe nothing. If it has, we stop all further work, and a Qualifying Outcome from the letter already sent can still be charged.
Pull your free reports from annualcreditreport.com and upload them to Cheating Debt. We'll show you every collection account and negative item on all three reports, and exactly what to do next, in your own dashboard.
100% free. No card, no subscription. Know exactly what's on your report before you dispute anything.
Get My Free Debt Cheat Sheet →